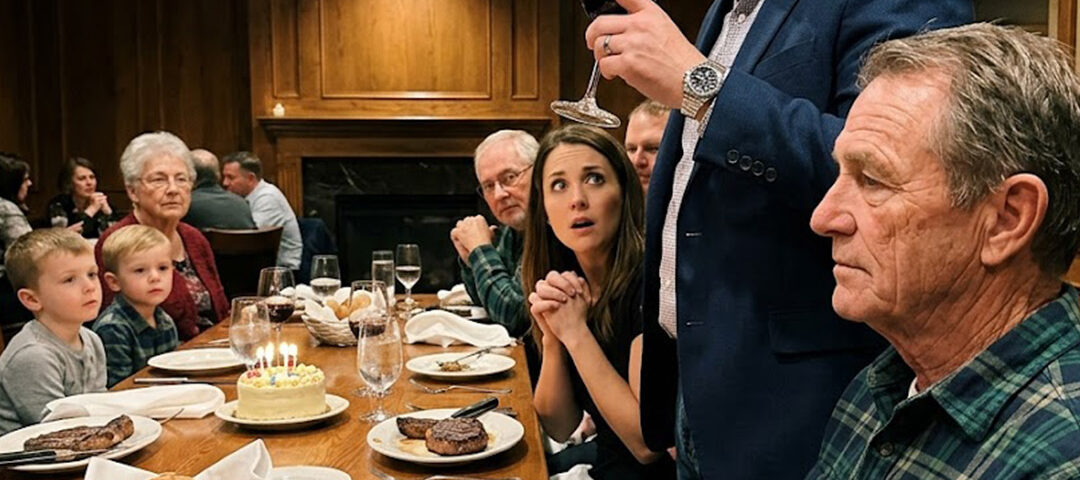
So I kept most of the financial details private.
Mark knew I had helped, of course, but he didn’t always know the exact amounts.
Emily knew more, but even she didn’t see the whole picture because the help came in pieces over years.
Neither did I.
Not until I sat down with six years of bank statements, canceled checks, electronic transfers, contractor invoices, and old emails.
I used a yellow legal pad and the same calculator I had once used for job estimates.
When I finished, the number at the bottom of the page was just over $183,000.
I stared at it for a long time.
It wasn’t the amount alone that bothered me.
I had given that money freely.
What bothered me was how ordinary the giving had become.
A gift should still feel like a gift to the person receiving it.
Ours had started to feel like a utility.
Always there.
Expected to work.
Only noticed when something went wrong.
Mark had changed gradually.
When he and Emily first married, he thanked me for everything.
Sometimes too much.
If I picked up dinner, he thanked me twice.
When I helped with the house, he shook my hand and told me he would never forget it.
But over time, the language changed.
“Richard can probably cover it.”
“Your dad’s doing fine.”
“Why should we put this on a credit card when he has the money?”
Emily repeated some of those comments to me, usually with an uncomfortable look on her face.
I should have addressed it then.
Instead, I made excuses.
Mark was under pressure.
The business was young.
The kids were expensive.
Every family went through rough stretches.
Besides, I had enough.
That last thought became my favorite excuse.
I had enough.
Enough to help with the roof.
Enough to cover a few mortgage payments.
Enough to take pressure off Emily.
Enough to keep Mark’s business problem from becoming Emily’s problem.
What I never asked was whether I would always have enough if I continued treating everyone else’s emergencies as my responsibility.
Susan had asked me that exact question during a phone call before my birthday.
“How many years are you planning for, Richard?”
“As many as I get.”
“That isn’t a financial plan.”
I laughed when she said it.
She didn’t.
At sixty-five, I could easily live another twenty or twenty-five years. Maybe longer. My savings had to cover property taxes, health expenses, home repairs, inflation, and whatever care I might need later in life.
I was comfortable.
I was not endlessly wealthy.
There is a large difference between the two.
Mark never seemed to understand that because he measured money by what people could see.
He thought the man with the new vehicle was doing better than the man driving a ten-year-old pickup.
After three decades in construction, I knew better.
I had watched men climb out of trucks that cost more than they earned in a year and spend lunch complaining about minimum payments.
I had also worked beside men in faded work shirts who owned their homes outright, carried no credit card balance, and slept just fine at night.
Security rarely announces itself.
Neither does trouble.
At nine the morning after my birthday, I sat across from Susan in her office.
She had known Carol well enough to ask about her by name for years after she died.
That mattered to me.
There are professionals who know your paperwork, and there are professionals who understand your life.
Susan understood both.
She slid a folder across her desk.
“I heard there was a birthday dinner.”
“Emily called you?”
“No. You mentioned it was coming up.”
“Right.”
She studied my face.
“It went well?”
“My son-in-law asked me how it felt to be a failure after sixty-five years.”
Susan leaned back in her chair.
“He said that at your birthday dinner?”
“In front of everybody.”
“What did you say?”
“I told him this failure wasn’t paying his bills anymore.”
For the first time that morning, Susan smiled.
Not because she found the situation funny.
Because she knew me.
“You’ve made your decision, then.”
“I think I have.”
“Think?”
I looked at the folder between us.
“I don’t want to hurt Emily.”
“That wasn’t my question.”
I knew it.
That was one reason I trusted her.
“I’m done subsidizing their household.”
She nodded.
“Then we can work with that.”
The folder contained updated estate planning documents, beneficiary information, notes about my townhouse rental, and projections for retirement spending under several scenarios.
Susan showed me what would happen if I continued sending Emily and Mark money at roughly the pace I had been.
The numbers didn’t say I would be broke next year.
They said something more realistic and therefore more frightening.
They said I would slowly reduce the cushion that protected me from the things nobody can predict at sixty-five.
A major home repair.
A long illness.
Higher property taxes.
Years of rising health care costs.
The possibility that I might eventually need help living on my own.
The possibility that I might simply live much longer than my father had.